Construction Loans Canberra
We arrange the finance for your build: land settled first, then funds released to your builder at each stage against a fixed-price contract. Construction loans Canberra buyers use work that way whether you are taking a house and land package in Whitlam or rebuilding on an established block, and it costs you nothing to have us set it up.
Five draws, not one
Slab, frame, lockup, fixing, completion. The lender pays your builder at each stage and you are charged interest only on what has been drawn so far.
Standard fixed-price building contract, August 2026
What We Arrange For A Build
We arrange finance that settles the land first, then releases funds to the builder at each construction stage against a fixed-price contract. That covers a house and land package, a knockdown rebuild, and building on a Canberra block you already hold.
Your build brings checks a purchase does not. The lender assesses your builder and your contract as well as you, and it values the property on completion, from the plans rather than from what is standing on the block today. If that on-completion valuation lands short you have to cover the difference in cash, so we would rather show you that exposure before you sign the building contract than after.
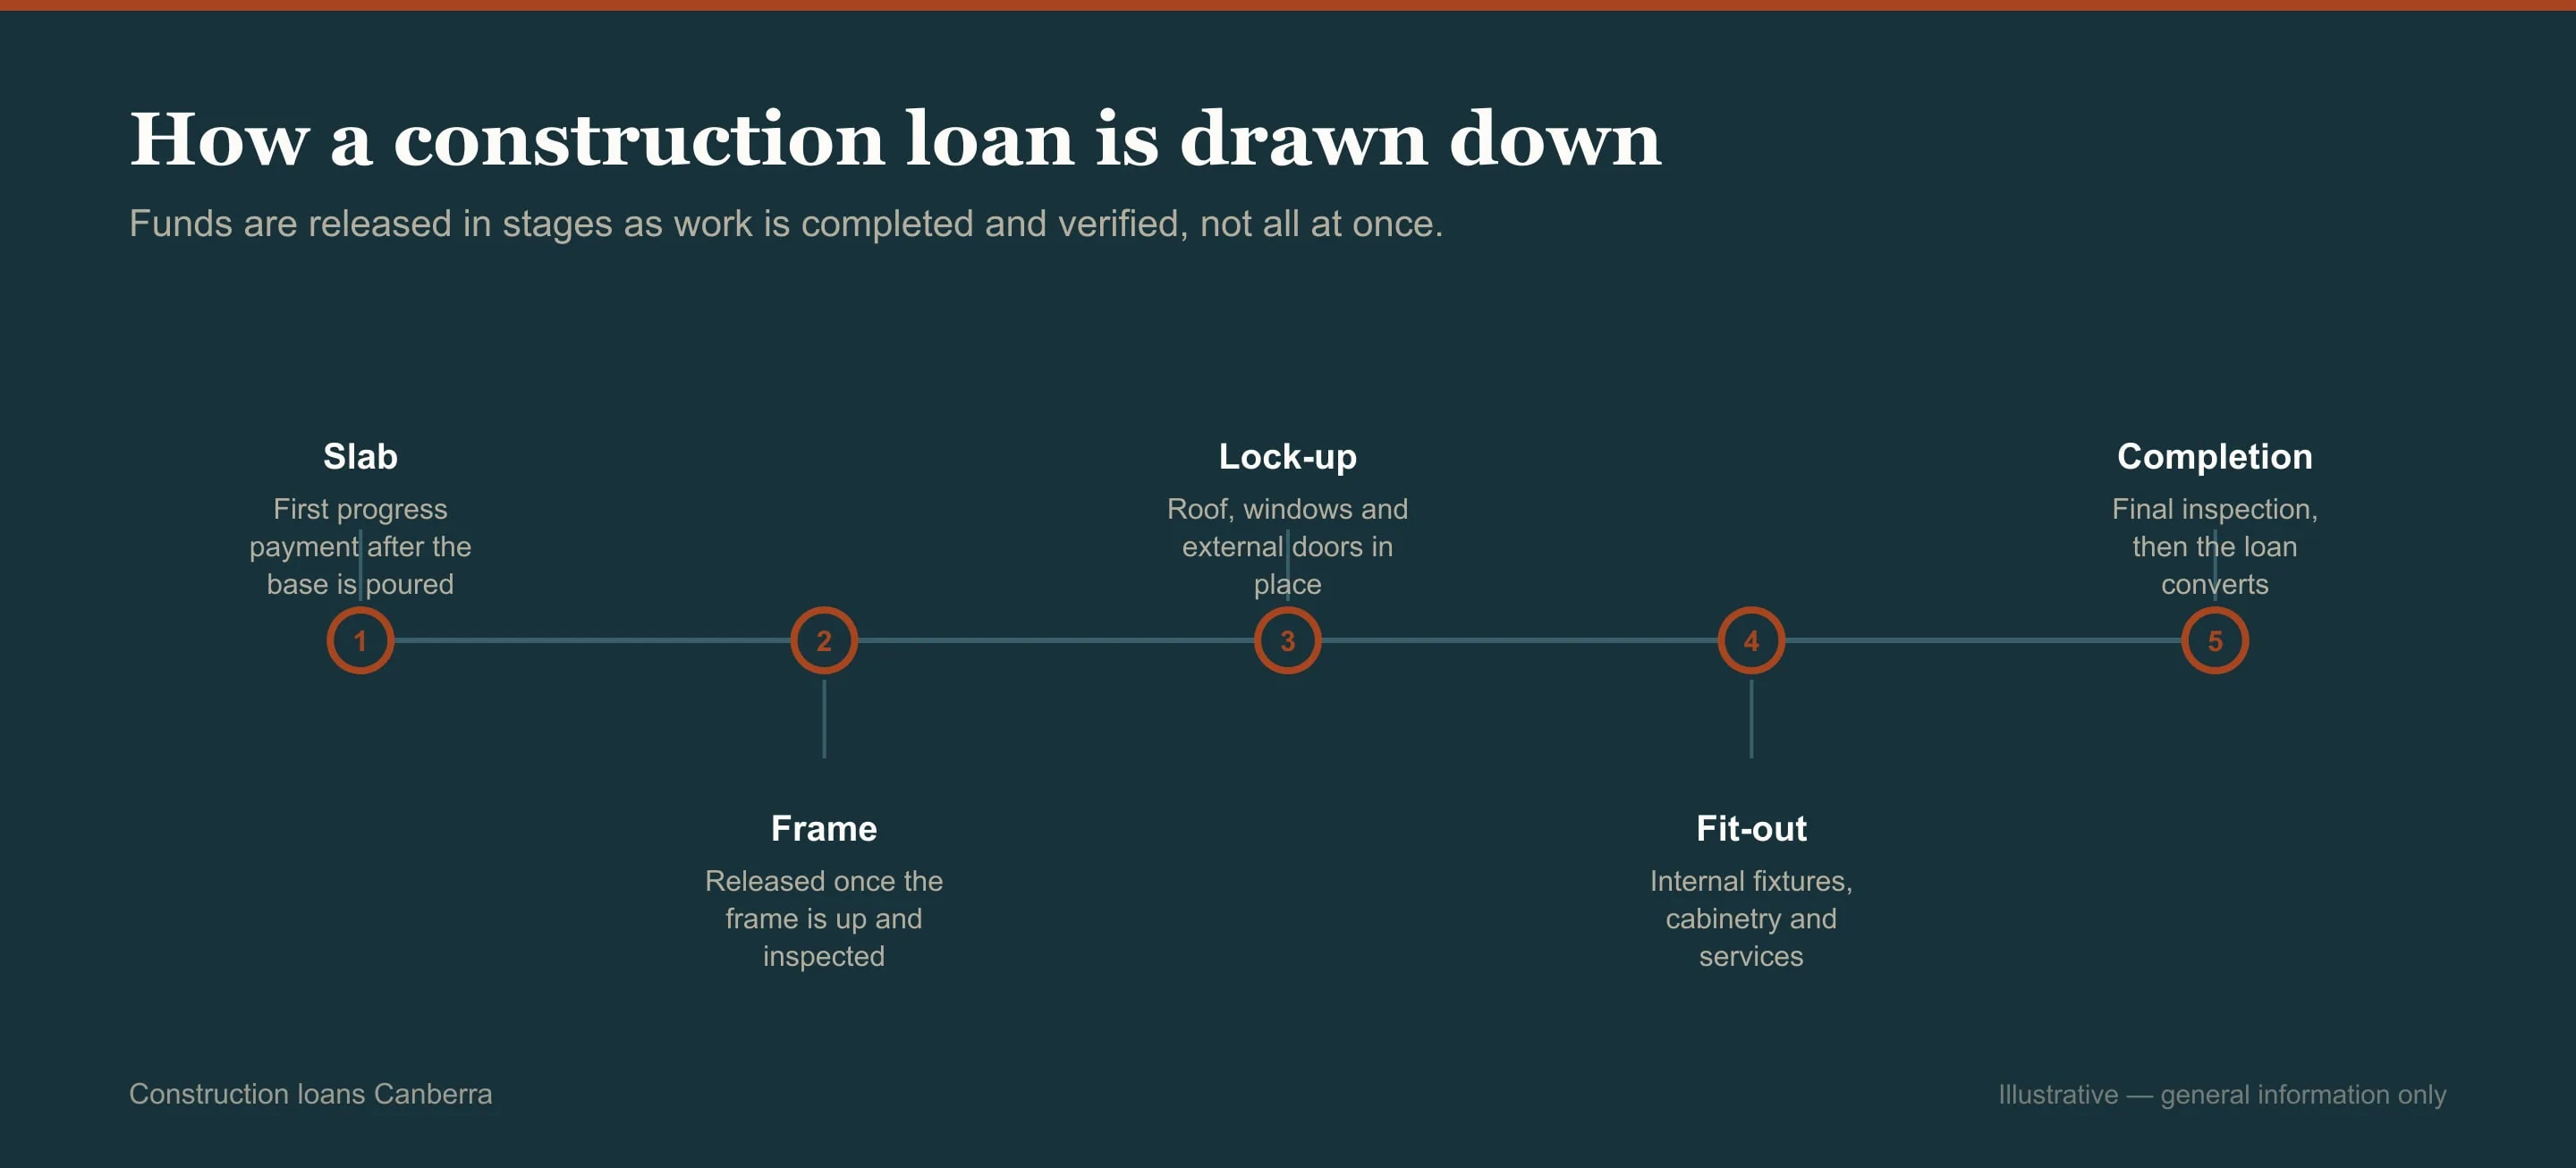
How Your Canberra Builder Gets Paid
Five stages is the standard structure we set up on a Canberra build. At each one your builder invoices and the lender inspects or verifies before any funds move, and we chase the release when it stalls.
-
Slab
The foundation is poured. This is usually the first construction drawdown, after the land has already settled.
-
Frame
The structural frame is up and inspected. The most visible jump in progress and usually a substantial draw.
-
Lockup
External walls, roof, windows and doors are in and the building can be secured.
-
Fixing
Internal fit-out: cabinetry, plasterboard, internal doors and fittings.
-
Completion
Final works and handover. The lender inspects before the last release and the loan converts to a normal principal-and-interest home loan.
Through the build you pay interest only on what has been drawn so far, so your repayments start small and step up with each release. Most lenders keep the loan interest-only until completion. If you are paying rent at the same time we model the two together, because that overlap is the part of a build that catches people out financially.
What Your Contracts Do To The Duty
If you are building in the Molonglo Valley or the northern Gungahlin release areas, your land is generally sold separately from the build, and that separation has a direct financial consequence for you.
Where your Canberra land and your building work sit under genuinely separate contracts, the ACT Revenue Office charges conveyance duty on the land contract alone rather than on the completed house-and-land value. It treats a single contract for a finished dwelling differently, and the gap between those two outcomes is real money to you.
So it is a structuring question to settle before anything is signed. We ask to see both contracts early and will flag it when the structure looks like it matters to your duty position. Confirming the treatment against your specific contracts is your conveyancer’s call, because that part is legal work, but you should be hearing about it from us in time to act on it.
Which Route You Are Taking
Two ways into a Canberra build, and lenders treat them very differently. Tell us which you are on and we will size the finance accordingly.
House and land
The common route in the Canberra growth suburbs, and the one most lenders are comfortable with: your land settles first on its own timeline, then the construction facility funds the build in stages. What we watch on your behalf is the gap between land settlement and construction start, because you are carrying the land debt with nothing built on it in the meantime. A long delay there is a real cost that never appears in the sales material, so we build it into the figures we give you.
Owner-builder
Considerably harder for us to finance, and we will tell you so at the outset. Most lenders either decline owner-builder projects outright or cap the ratio well below normal, because there is no fixed-price contract and no accredited builder standing behind the work. Expect a larger deposit from you, closer scrutiny of your costings, and a much shorter list of willing lenders. We will price it honestly against what a licensed builder would cost you, because that comparison usually settles the question.
Whether The Land Rent Scheme Is Open To You
The Land Rent Scheme is specific to Canberra and worth us checking for you, because it takes the land cost out of what you have to finance at the start. Rather than buying the land outright you rent it from the ACT Government and build on it, and the lease can be converted to a nominal Crown lease later.
Two constraints decide whether it is actually available to you. Only the discounted two per cent rate remains open to new entrants, since the standard four per cent rate closed to new applicants on 1 October 2013. And eligibility for that discounted rate is income-tested and limited to low-to-moderate income households. We test you against it before you build a plan around it.
The financing side is where we are most useful to you, because not every lender will write a loan against a land rent title. Beyond Bank, Police Bank and Bank Australia are among those that will and the list is genuinely short, so we confirm appetite with a lender before you commit to the scheme rather than afterwards. Being accepted into a scheme you then cannot finance is an expensive position, and it is entirely avoidable with one call.
What We Watch On A Build Budget
The levers we manage on your Canberra construction loan, beyond the usual income and deposit questions.
- Your contract type
- Lenders want a fixed-price contract with a licensed builder. If yours is cost-plus we will tell you early, because the final figure is not known at approval and that narrows who will fund you.
- The on-completion valuation
- The lender values what your plans describe rather than the block as it stands. If that lands below the total of land plus build you cover the difference in cash, so we stress-test the figure with you before you sign.
- How your draws are staged
- Every release needs an inspection or verification, so non-standard staging adds administration and can add cost to you. We keep the schedule conventional unless your build genuinely requires otherwise.
- Who your builder is
- The lender assesses your builder alongside you, and an unaccredited or newly established one shortens the list of lenders available. Send us the builder’s details with the contract and we will check the position before lodging.
- Variations once you start
- Changes you make after the contract is signed are typically funded in cash rather than added to the loan, so we ask you to hold a separate allowance for them rather than assuming the facility will stretch.
How We Run Your Canberra Build Finance
Longer than a standard Canberra purchase, because the land and the build settle at different times and the lender assesses both.
-
Capacity and structure
Income, deposit and how the land and build are contracted. If you are also paying rent through the build, that is modelled here.
-
Contracts and plans to the lender
The fixed-price building contract, the plans and the specifications. The lender assesses the builder as well.
-
Approval and on-completion valuation
The valuer prices the finished house from the plans. This is the step most likely to produce a surprise.
-
Land settles
The land portion draws down first. Interest starts on that amount only.
-
Staged draws through the build
Slab, frame, lockup, fixing, completion. Your builder invoices, the lender verifies, funds are released.
-
Completion and conversion
Final inspection, last release, and the loan converts to an ordinary principal-and-interest home loan.
Worth having to hand: your payslips and card limits, the land contract, and the fixed-price building contract with the plans and specifications once your builder has issued them. If you will be paying rent through the build, have that figure too, because the lender counts it while the house is going up.
Construction Loans Questions
How does a construction loan pay out?
In stages rather than as a single settlement. The land portion settles first, then funds are released to your builder at slab, frame, lockup, fixing and completion. Your builder invoices at each stage and the lender verifies or inspects before releasing the money.
Do I pay interest during the build?
Yes, but only on what has been drawn so far, so the repayment starts small and steps up with each release. Most lenders keep the loan interest-only until completion, then convert it to principal and interest. If you are renting through the build, model both outgoings together.
Can I finance a house and land package?
Yes, and it is the standard route in the Molonglo Valley and the northern Gungahlin release areas. Land and build are usually separate contracts, which affects how the ACT Revenue Office charges conveyance duty. Where they are genuinely separate, it charges duty on the land contract only. Have your conveyancer confirm the treatment for your contracts.
What deposit do I need to build?
Broadly similar to a purchase, calculated against the total of land plus build, with the on-completion valuation as the reference point. The complication is that if the valuation comes in below that total, you cover the shortfall in cash. Owner-builder projects need substantially more deposit, and far fewer lenders will write one in Canberra.
Can I get a loan on a land rent block?
Some lenders will and many will not. Beyond Bank, Police Bank and Bank Australia are among those that finance land rent titles. Only the discounted two per cent rate is open to new entrants, since the standard rate closed to new applicants on 1 October 2013, and eligibility is income-tested. Confirm lender appetite before you commit to the scheme, because it is a short list and the check is quick.
What does it cost me to have you arrange the build finance?
Nothing. The lender that funds the build pays us, and we disclose what we are paid in writing before you proceed. That includes reading your land and building contracts, checking the duty structure and stress-testing the on-completion valuation. It still costs you nothing if we conclude the numbers do not work and you should not sign.
What do you need from me, and how long does it take?
The land contract, the fixed-price building contract with plans and specifications, your builder’s details, and the usual payslips, statements and card limits. From those we can map how the draws will run and where the risks sit. Expect the overall process to take longer than a standard purchase, since the land and the build settle at different times and the lender assesses your builder as well as you.
Get The Build Financed Before You Sign
From the land contract and the building contract we can show you how your draws will run, what the on-completion valuation needs to support and what a shortfall would cost you, whether your contract structure changes the duty, and the interest you will carry through the build alongside any rent. Anyone building across Canberra and the surrounding region can have that done before committing, at no cost.
Ask about construction loans
Nothing here touches your credit file.