Refinancing Canberra
We read the loan you are in, compare it against what the Canberra market would give you today, and tell you plainly whether switching is worth it. The review costs you nothing and takes one conversation. If you are better off staying put, that is what we will say.
80% of the property value
Take cash out above this line and Lenders Mortgage Insurance comes back, even though you paid it once already. It is the number most refinances are built around.
Lender policy, current at August 2026
What A Refinance Review Involves
We read your current loan: rate, structure, remaining term, features and any fixed period. Then we compare it against what the market would offer you today. If a switch is worth making, we prepare the application, manage the valuation and coordinate the discharge with your existing lender.
Sometimes what we tell you is to stay. A loan with a small balance and a short remaining term rarely justifies the effort, and a fixed rate carrying a large break cost is often worth sitting out. You being told to leave it alone is a legitimate outcome of the review, it costs you nothing either way, and it happens on a fair share of the Canberra loans we look at.
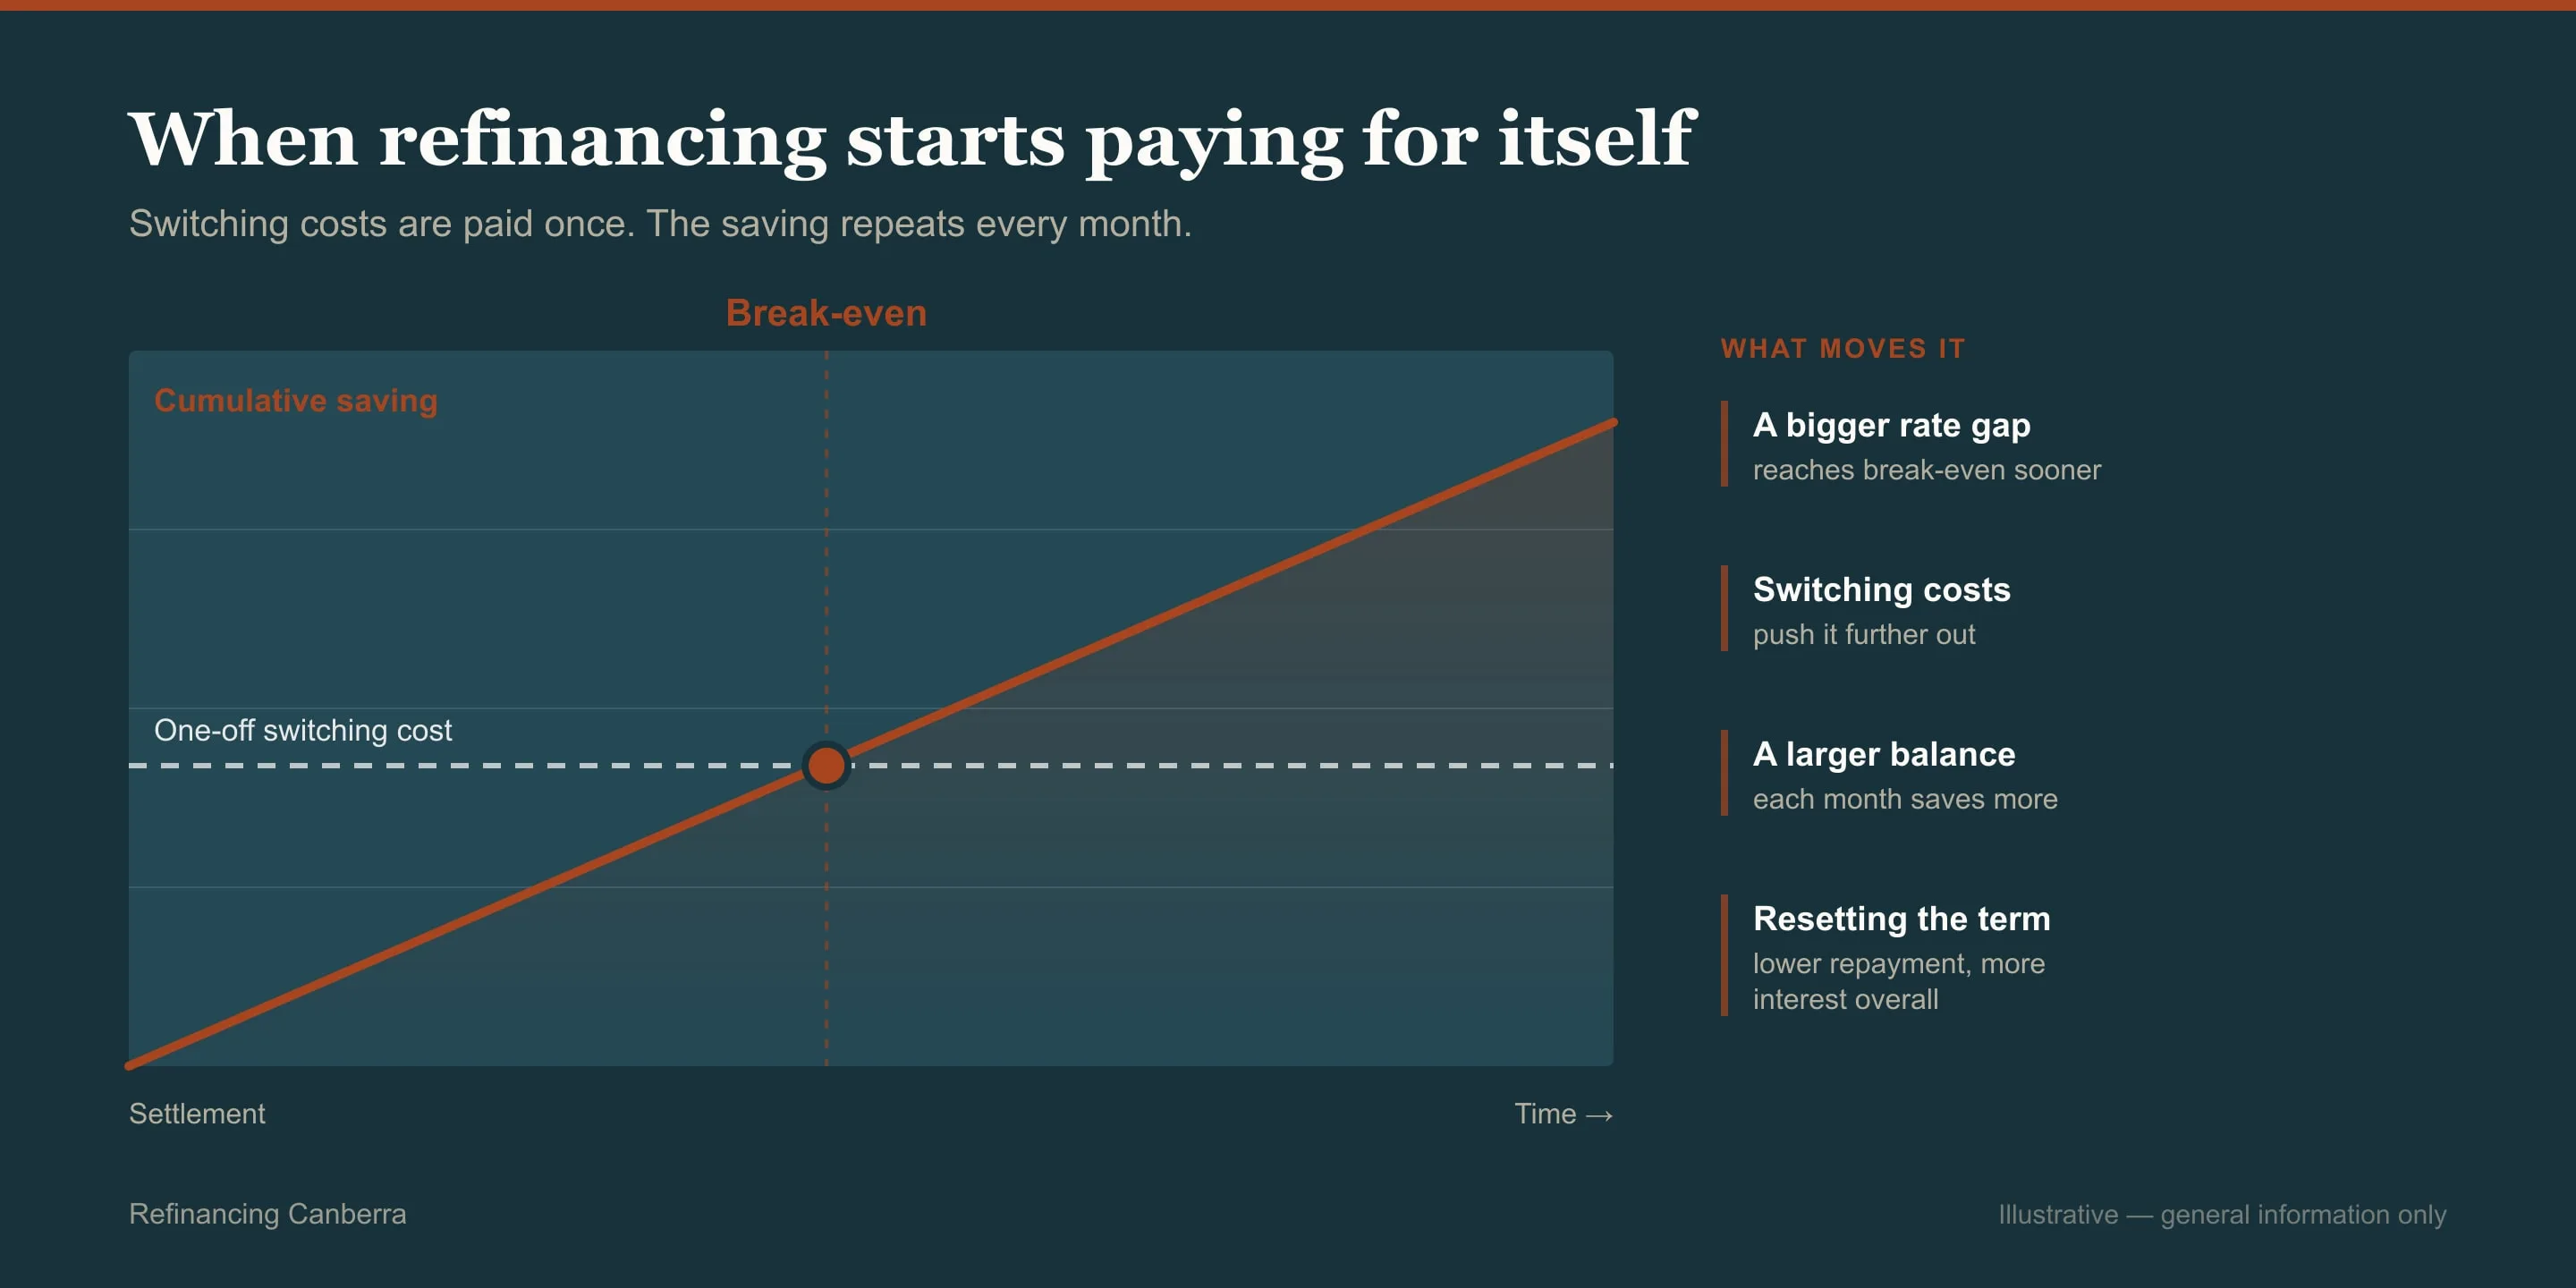
Whether Switching Is Worth It For You
The clearest case we see in Canberra is a loan two or more years old that has never been renegotiated. Lenders price new business more sharply than the loans already on their books and the gap widens quietly, so if nobody has asked your lender to sharpen your rate since settlement, that is the first thing we do. Sometimes it settles the question without you moving at all.
The second case is that what you need has changed: an interest-only period ending, a fixed term expiring, a loan with no offset now that you are holding savings, or a Canberra home that has become a rental. Repricing will not fix a structural mismatch, so where that is what we find, we rebuild the structure rather than chase a few points off the rate.
The third is equity. If your property has risen since you bought, your loan-to-value ratio has fallen without you doing anything, and we can often use that to move you into a better tier or release funds. What limits it is serviceability. You are still assessed at three percentage points above the product rate under the APRA buffer held at that level on 23 July 2025, although some lenders now apply a reduced buffer to a like-for-like refinance where you have a clean record and are not increasing the loan. Knowing which lenders do that is often what makes your refinance possible, so we check it before assuming your equity is usable.
Taking Cash Out Of Your Canberra Property
If you want funds released for a renovation, a deposit on another property or a business purpose, that is cash-out, and it is the most scrutinised refinance there is. We would rather set your expectations before lodgement than have the file stall.
Two rules shape what you can do. Above 80% of your Canberra property value the lender charges Lenders Mortgage Insurance again even though you paid a premium on the original loan, so we work out how much equity can come out while keeping you under that line. And the lender takes your stated purpose seriously: it will ask what the money is for and, above modest amounts, ask you to evidence it, so we get that documented up front instead of letting a vague answer slow the file down or sink it.
We also check the purpose you have in mind against the specific lenders on your shortlist, because some purposes sound perfectly reasonable and still read poorly on an application. You want to hear that from us while there is time to structure it differently, not from an assessor after lodgement.
If You Are Locked Into A Fixed Rate
Being on a fixed rate does not shut you out of a refinance, and this is where we most often have to correct what someone has been told.
You can break a fixed loan
Nothing prevents you. What applies is a break cost, and it is not a set fee. Your lender calculates it from the movement in its own funding costs since you fixed, so it can be trivial or very large. We cannot estimate it reliably and nor can any calculator, so the first thing we ask you to do is request a written figure from your lender. Everything else we work out for you depends on that number, and it costs you nothing to obtain.
Switching out of fixed
If your break cost comes back small, or your fixed term is nearly up, we move you to variable and recover the features fixed loans suppress: full offset, unlimited extra repayments and redraw. If it comes back large, we will tell you to wait, and then prepare the refinance so it completes the week your fixed term expires. Timing the application so you switch without a gap or a break cost is work we do rather than something you have to diarise.
Whether To Roll Other Debts Into The Loan
If you are carrying credit cards or a personal loan, folding them into the mortgage will drop your monthly outgoing immediately, because the rate is lower and the term far longer. That appeal is real and we will not pretend otherwise.
What we will do is show you the other side, because it usually gets glossed over. A balance that would have cleared in three years can end up spread across twenty-five, and the total interest you pay over that period can exceed what the original debt would have cost even at a much higher rate. It also converts unsecured debt into debt secured against your Canberra home, which changes what is at stake if things go wrong.
The Best Interests Duty makes that a live obligation for us rather than a caveat in the fine print: where consolidation would leave you worse off over the life of the loan, we have to tell you so. Where it genuinely is the right move, we split the consolidated portion over a shorter term so it still clears quickly and you keep the cash-flow relief without the twenty-five-year tail. We will also make sure the accounts being paid out are actually closed, because lenders only treat them as cleared for assessment if they are.
Two Checks We Run Before Lodging Your Refinance
If you are selling and buying at once, we look at portability first. That means keeping your existing loan and substituting the new property as security, which avoids a full new application and can avoid break costs on a fixed loan altogether. It only works where the timing lines up and the new property satisfies your lender, so we test both before you rely on it.
The second check is local and applies to every Canberra refinance we lodge. Where the remaining term on your Crown lease is short, a lender may require you to apply for a further lease before the refinance can complete, and that application is not instantaneous. We pull the lease term at the start of the file so you are not stalled at approval waiting on something that could have been started weeks earlier.
How We Run Your Canberra Refinance
Four to six weeks is typical on a Canberra refinance, from first conversation to settlement. The discharge from your existing lender is usually the slowest part and is largely outside our control.
-
Your current loan, read properly
A recent statement shows the rate, balance, term, structure and any fixed expiry. If it is fixed, ask your lender for a written break cost at the same time.
-
Equity and valuation
We estimate your current loan-to-value ratio, then order a valuation on the Canberra property. This decides which tiers and which lenders are open to you.
-
Compare and decide
The comparison covers rate, structure and features, with the cost of switching included. Staying is a valid outcome and gets said plainly.
-
Application and approval
Lodged with the new lender. Cash-out purposes are documented here if any funds are being released.
-
Discharge and settlement
Your current lender is served a discharge authority. Allow a couple of weeks for it. The two lenders settle between themselves and your repayments start with the new one.
Worth having to hand: your most recent loan statement, your current payslips, and the limits on any cards or personal loans you have taken on since you last applied. Those last two are what most often move a refinance from comfortable to marginal, because you are assessed again from scratch.
Refinancing Questions
Can I refinance while I am on a fixed rate?
Yes. Nothing stops you, but a break cost applies and your lender calculates it from its own funding position rather than charging a set fee. Ask your current lender for a written figure before you do any other calculation. If it is large, the usual approach is to prepare the refinance so it completes the week the fixed term expires.
How much equity do I need?
A straightforward refinance generally wants you at or under 80% of what the Canberra property is worth, which stops the lender charging Lenders Mortgage Insurance again. We can refinance you above that, but the lender re-triggers LMI, and you would be paying a second premium on a loan you already insured once.
Does refinancing reset my loan term?
By default yes. Most refinances start a new thirty-year term, which lowers the repayment and raises the total interest paid. You can ask for the remaining term to be matched instead. It is worth deciding deliberately rather than accepting the default.
Can I consolidate credit cards and personal loans into the mortgage?
Usually, if you have the equity and the servicing. The repayment drops immediately. The risk is that short-term debt becomes long-term debt secured against your home, and the total interest over twenty-five years can exceed what you would have paid at a higher rate over three. Splitting the consolidated amount over a shorter term keeps the benefit without that outcome.
Will refinancing hurt my credit file?
A single application records a single enquiry, which is normal and expected. What causes problems is several applications across different lenders in a short period. We compare the market for you without lodging anything, then lodge once with the lender we have recommended, so your file carries one enquiry rather than a cluster.
What does the review cost me?
Nothing, whatever the outcome. We are paid by the lender that writes the new loan, and that payment is disclosed to you in writing before you proceed. If the review concludes you should stay where you are, you pay us nothing and owe us nothing, which is exactly why we are willing to say it.
How long does a refinance take and what do you need from me?
Four to six weeks from first conversation to settlement is typical, with the discharge from your existing lender usually the slowest part. To start we need a recent statement showing your rate, balance, term, structure and any fixed expiry, plus payslips and card limits. If you are on a fixed rate, ask your lender for a written break cost at the same time. That one figure decides most of the answer.
Have Your Current Loan Reviewed
From a recent statement we can tell you what your loan is costing you against what the market would offer today, the cost of switching including any break figure, and a straight recommendation either way. The review is free, it takes one conversation, and if staying put is the better outcome we will tell you so. Owners across Canberra and the surrounding towns are welcome to get in touch.
Ask about refinancing
Nothing here touches your credit file.