Investment Loans Canberra
We work out what you can borrow once the rent is counted the way a lender counts it, model what the property will actually cost you to hold each year, and structure the loan around both. It costs you nothing, because the lender pays us, and you get the numbers before you offer rather than after settlement.
From the first dollar
The ACT charges land tax on a rented dwelling with no tax-free threshold at all. Across the border, NSW gives a general threshold before land tax starts.
ACT Revenue Office, 2026 land tax year
What We Structure For You
We work out what you can borrow with rental income included, structure the loan and any equity release, and lodge the application. Where you already hold Canberra property, that includes reviewing how the existing loans are set up, since the structure across a portfolio affects what the next lender will approve.
The modelling matters to you as much as the approval does. A Canberra property that services on paper can still run at a monthly shortfall once the real holding costs are in it, so we put that figure in front of you before you commit rather than letting the first land tax notice deliver it.
How Lenders Read Your Rent On Investment Loans Canberra Landlords Take On
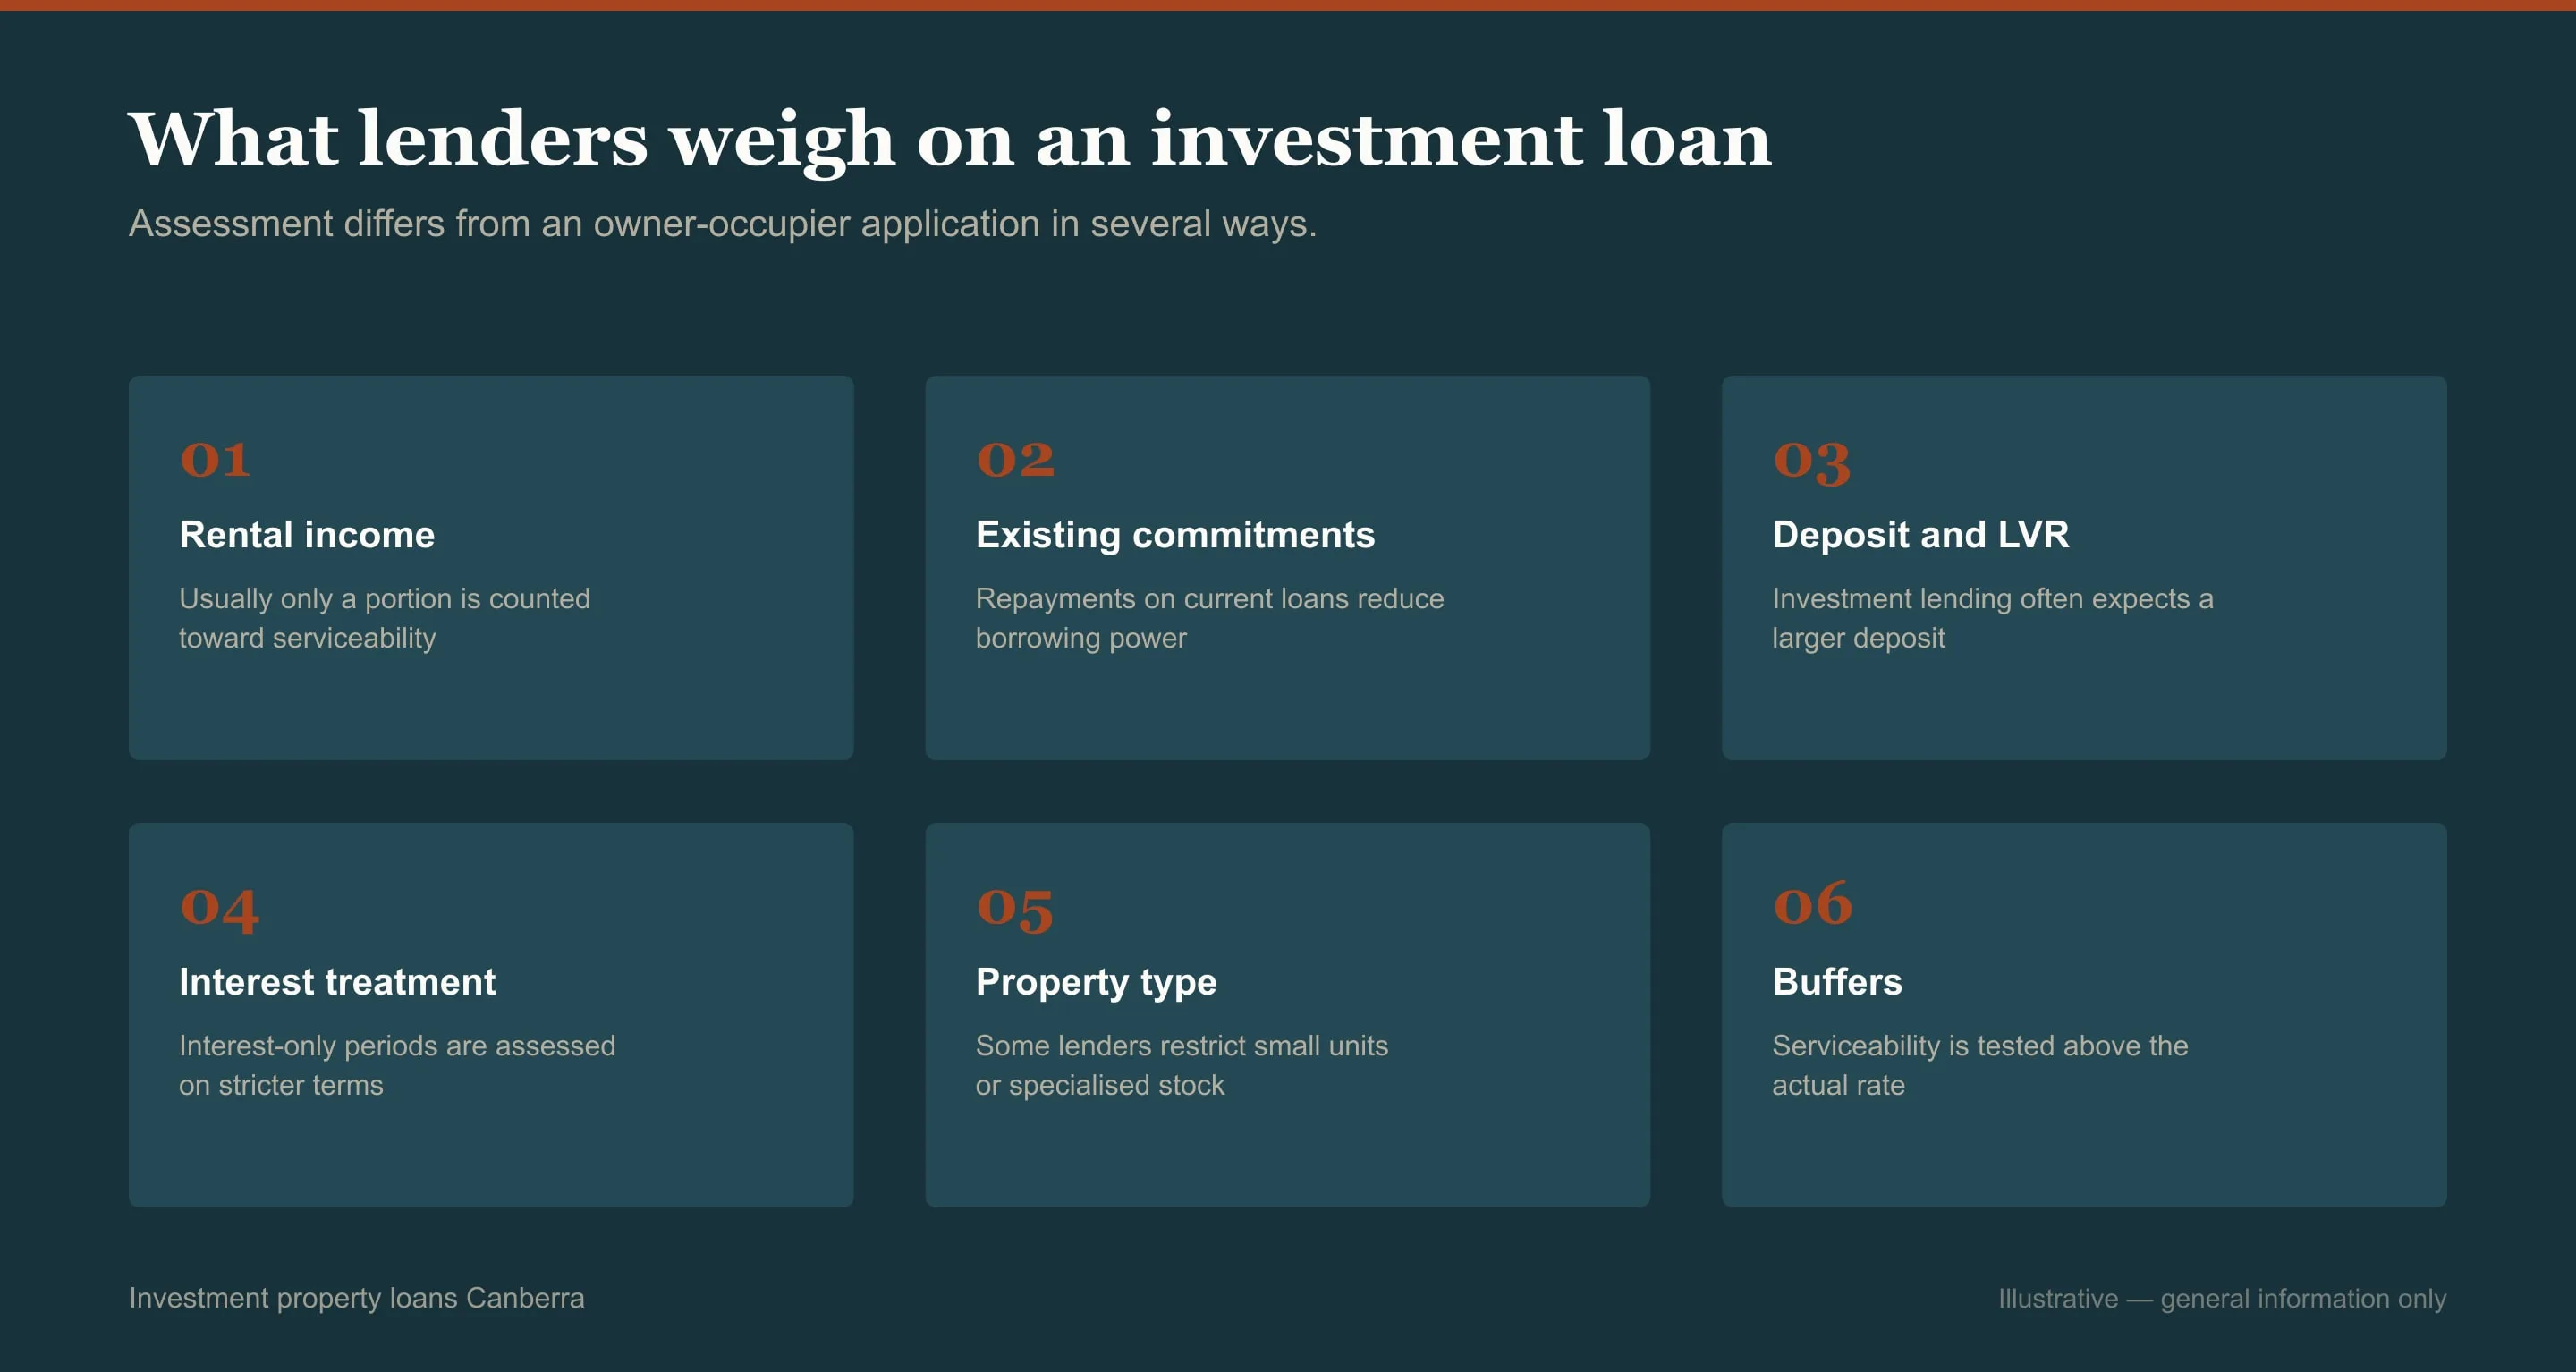
Your rent will not be counted at face value, so we do not quote you a figure that assumes it will be. Most lenders shade gross rent to around 80% to absorb vacancy, management fees and maintenance, which means the other twenty per cent has to come out of your own income before the loan services at all. We run your numbers shaded from the start, and the range you get back is one that survives the lender doing the same thing.
The APRA buffer applies to you here as everywhere. You are assessed at three percentage points above the product rate, held at that level on 23 July 2025, and every investment loan you already hold is assessed at its own buffered rate too. That is why your third or fourth purchase is disproportionately harder than your second, and why we review your existing loans before telling you what the next one can be.
Interest-only is the lever most investors reach for and it does less than you would expect. It genuinely lowers what you pay each month, but the lender assesses your capacity over the residual principal-and-interest term that follows, so a five-year interest-only period on a thirty-year loan is assessed over the remaining twenty-five and your servicing gets tighter in the calculator even as your cash outgoing falls. We will tell you when that trade is worth making for your position and when it is quietly costing you borrowing capacity you need.
Unit Versus House Yields In Canberra
Gross yields across Canberra, mid-2026. These move, so re-check them before you decide on one. They show the shape of the trade-off rather than a forecast.
| Property type | Gross yield | What it means for you |
|---|---|---|
| Units | ~5.4% | The yield play. Stronger cash flow, but lender restrictions on size and building density narrow which ones are financeable. |
| All dwellings | ~4.2% | The territory-wide midpoint, useful mainly as a benchmark against other capitals. |
| Houses | ~3.8% | Weaker cash flow, and houses have been outperforming units on capital growth. The land component is doing the work. |
Source: CoreLogic-derived market data, mid-2026. Yields are gross, before any holding costs.
Which Side Of The Border Costs You More To Hold
This is the local figure that changes your investment maths most and is missed most often, so we put it in front of you before you choose a suburb. The ACT charges land tax on any rented residential dwelling from the first dollar of land value. There is no tax-free threshold at all, and a fixed charge applies on top of the valuation-based component.
Cross the border and the position reverses: NSW general land tax does not begin until the land value passes a threshold of $1,075,000 for the 2026 land tax year, frozen at that level since 1 January 2025, and owner-occupied homes are exempt entirely.
So if you are weighing a rental in Tuggeranong against one in Googong, you are comparing a recurring annual cost rather than a one-off, and the yield figures above will not show it to you. The ACT front-loads less duty and recovers it through higher annual rates and land tax while NSW does the reverse, which means the better side depends on how long you intend to hold and what the land underneath is worth. We model both holding costs against your actual plan so the comparison is real; your accountant confirms the tax position itself, because what we do is finance rather than tax advice.
What We Weigh Before Recommending A Structure
The levers we work through on your Canberra purchase, in roughly the order they change the answer.
- How the rent is shaded
- Around 80% is common, but the exact treatment varies by lender, and some are more generous with an existing lease in place than with an appraisal.
- Annual holding costs
- Land tax from the first dollar in the ACT, rates, insurance, strata levies on a unit, and management. These do not appear in the yield figure.
- Loan-to-value ratio
- Above 80% triggers LMI, and investment LMI premiums generally run higher than owner-occupier. Investment lending is also usually priced above owner-occupier at the same ratio.
- Interest-only
- Improves cash flow, tightens the servicing assessment, and typically carries a premium over principal and interest.
- The property itself
- Small units and high-density buildings carry their own lending restrictions, which is a separate subject with its own page.
Releasing Equity To Buy The Next One
If you already own in Canberra, the equity in that property is usually your way into the second one. We review what is genuinely available to release once the buffer is applied, arrange the release, and structure it so your investment borrowing stays separate from the borrowing on your home.
That separation is the part we will insist on with you. Mixing investment and personal borrowing in one account makes your interest deductibility position messy and untangling it years later is difficult and sometimes impossible, whereas split loans or a separate facility keep the record clean from the day it settles. Setting the structure up is our job and it costs you nothing extra to do it properly; confirming the deductibility outcome is your accountant’s.
How An Investment Application Runs
Where you already own Canberra property, the first two steps take longer, because the lender has to assess every loan you already hold as well.
-
Position review
Existing loans, their rates and structures, current values, and your income. If you hold several properties this is where the ceiling becomes visible.
-
Servicing with rent included
We shade your Canberra rental income the way a lender will and assess your existing commitments at buffered rates, so you get a realistic borrowing figure rather than a gross one.
-
Structure
Whether to release equity, whether to go interest-only, and how to keep the investment borrowing separate from your home loan.
-
Pre-approval
Lodged with the lender whose policy handles your rental income and property type best.
-
Contract, valuation, settlement
The valuation matters more on investment purchases, particularly on units. A short valuation changes the deposit required at short notice.
Worth having to hand: your payslips, statements for every loan on property you already hold, and a rental appraisal or the existing lease for the place you are buying. Where you own more than one property, the existing loans matter more than the new one, because each is assessed at its own buffered rate.
Investment Loans Questions
How do lenders count my rental income?
Most shade gross rent to around 80% before it counts toward servicing, which covers vacancy, management and maintenance. The remaining twenty per cent has to be carried by your own income. The exact treatment varies between lenders, and some are more generous where a signed lease already exists.
What yields are Canberra units achieving?
Gross yields sat at roughly 5.4% for units and 3.8% for houses in mid-2026, with all dwellings around 4.2%. Units are the cash-flow play, houses have been stronger on capital growth. These figures move, so re-check before you decide on one. Remember gross yield is before land tax, rates, strata and management.
Does the ACT charge land tax on an investment property?
Yes, on any rented Canberra dwelling, from the first dollar of land value. There is no tax-free threshold and a fixed charge applies alongside the valuation-based component. This is materially different from NSW, where general land tax starts only above a threshold of $1,075,000 for the 2026 land tax year. Speak to your accountant about your own position.
Can I use equity in my home to buy an investment?
Usually, if the equity and the servicing are both there. The important part is structure. Keep the investment borrowing separate from your home loan rather than drawing both from the same account, so the record stays clean. Your accountant should confirm the deductibility treatment before you draw anything.
Is interest-only better for an investment loan?
It improves your cash flow and it is common for investors, but it makes the servicing assessment harder because the lender tests you over the shorter principal-and-interest term that follows, and it usually carries a rate premium. Whether it suits you depends on your cash-flow position and your plans for the property, so we model it both ways before you decide.
What do you need from me to model a purchase?
The listing or the address, a rental appraisal or the existing lease if there is one, your payslips and card limits, and statements for any loans on property you already hold. With that we can shade the rent, assess your existing commitments at their buffered rates, and give you a borrowing figure and an annual holding cost.
Do you charge investors a fee?
No. We are paid by the lender that writes the loan, and the amount is disclosed to you in writing before you proceed. That applies whether it is your first rental or your fourth, and it applies to the modelling as well. If the numbers say the purchase does not stack up, you have paid nothing to find that out.
Model The Purchase Before You Offer
Tell us about the property you are considering and we will work through the servicing with the rent shaded the way lenders shade it, the equity release if you need one, and the annual holding cost on both sides of the border so you can see what it really costs to keep. Investors buying across Canberra and the nearby NSW towns can have that done in a single conversation, at no cost and with nothing lodged.
Ask about investment loans
Nothing here touches your credit file.