Guarantor Home Loans Canberra
We structure a family guarantee so you can buy years earlier without paying Lenders Mortgage Insurance, and we set it at the smallest amount that gets you there. That size is the number that matters most, because a guarantee puts your parent’s home genuinely at risk until it is released. Guarantor home loans Canberra families arrange cost you nothing to have us assess, and we plan the exit before anyone signs.
Released under 80%
Once the loan falls below this share of the property value, the guarantee over the guarantor’s home can usually be lifted. Until then their property is genuinely at risk.
Lender policy, current at August 2026
What We Structure For Both Parties
Two people get assessed on a Canberra guarantee rather than one. We check your guarantor has the usable equity and can afford to be exposed, confirm you can service the whole loan on your own income, and cap the guarantee at the smallest figure the lender will take.
Your guarantor needs to understand exactly what they are exposed to and how they get out, and lenders will require them to take independent legal advice before they sign. We set the structure up so that release is achievable for them rather than theoretical, and we say so in writing before anything goes to a lender.
How The Guarantee Gets You In Without LMI
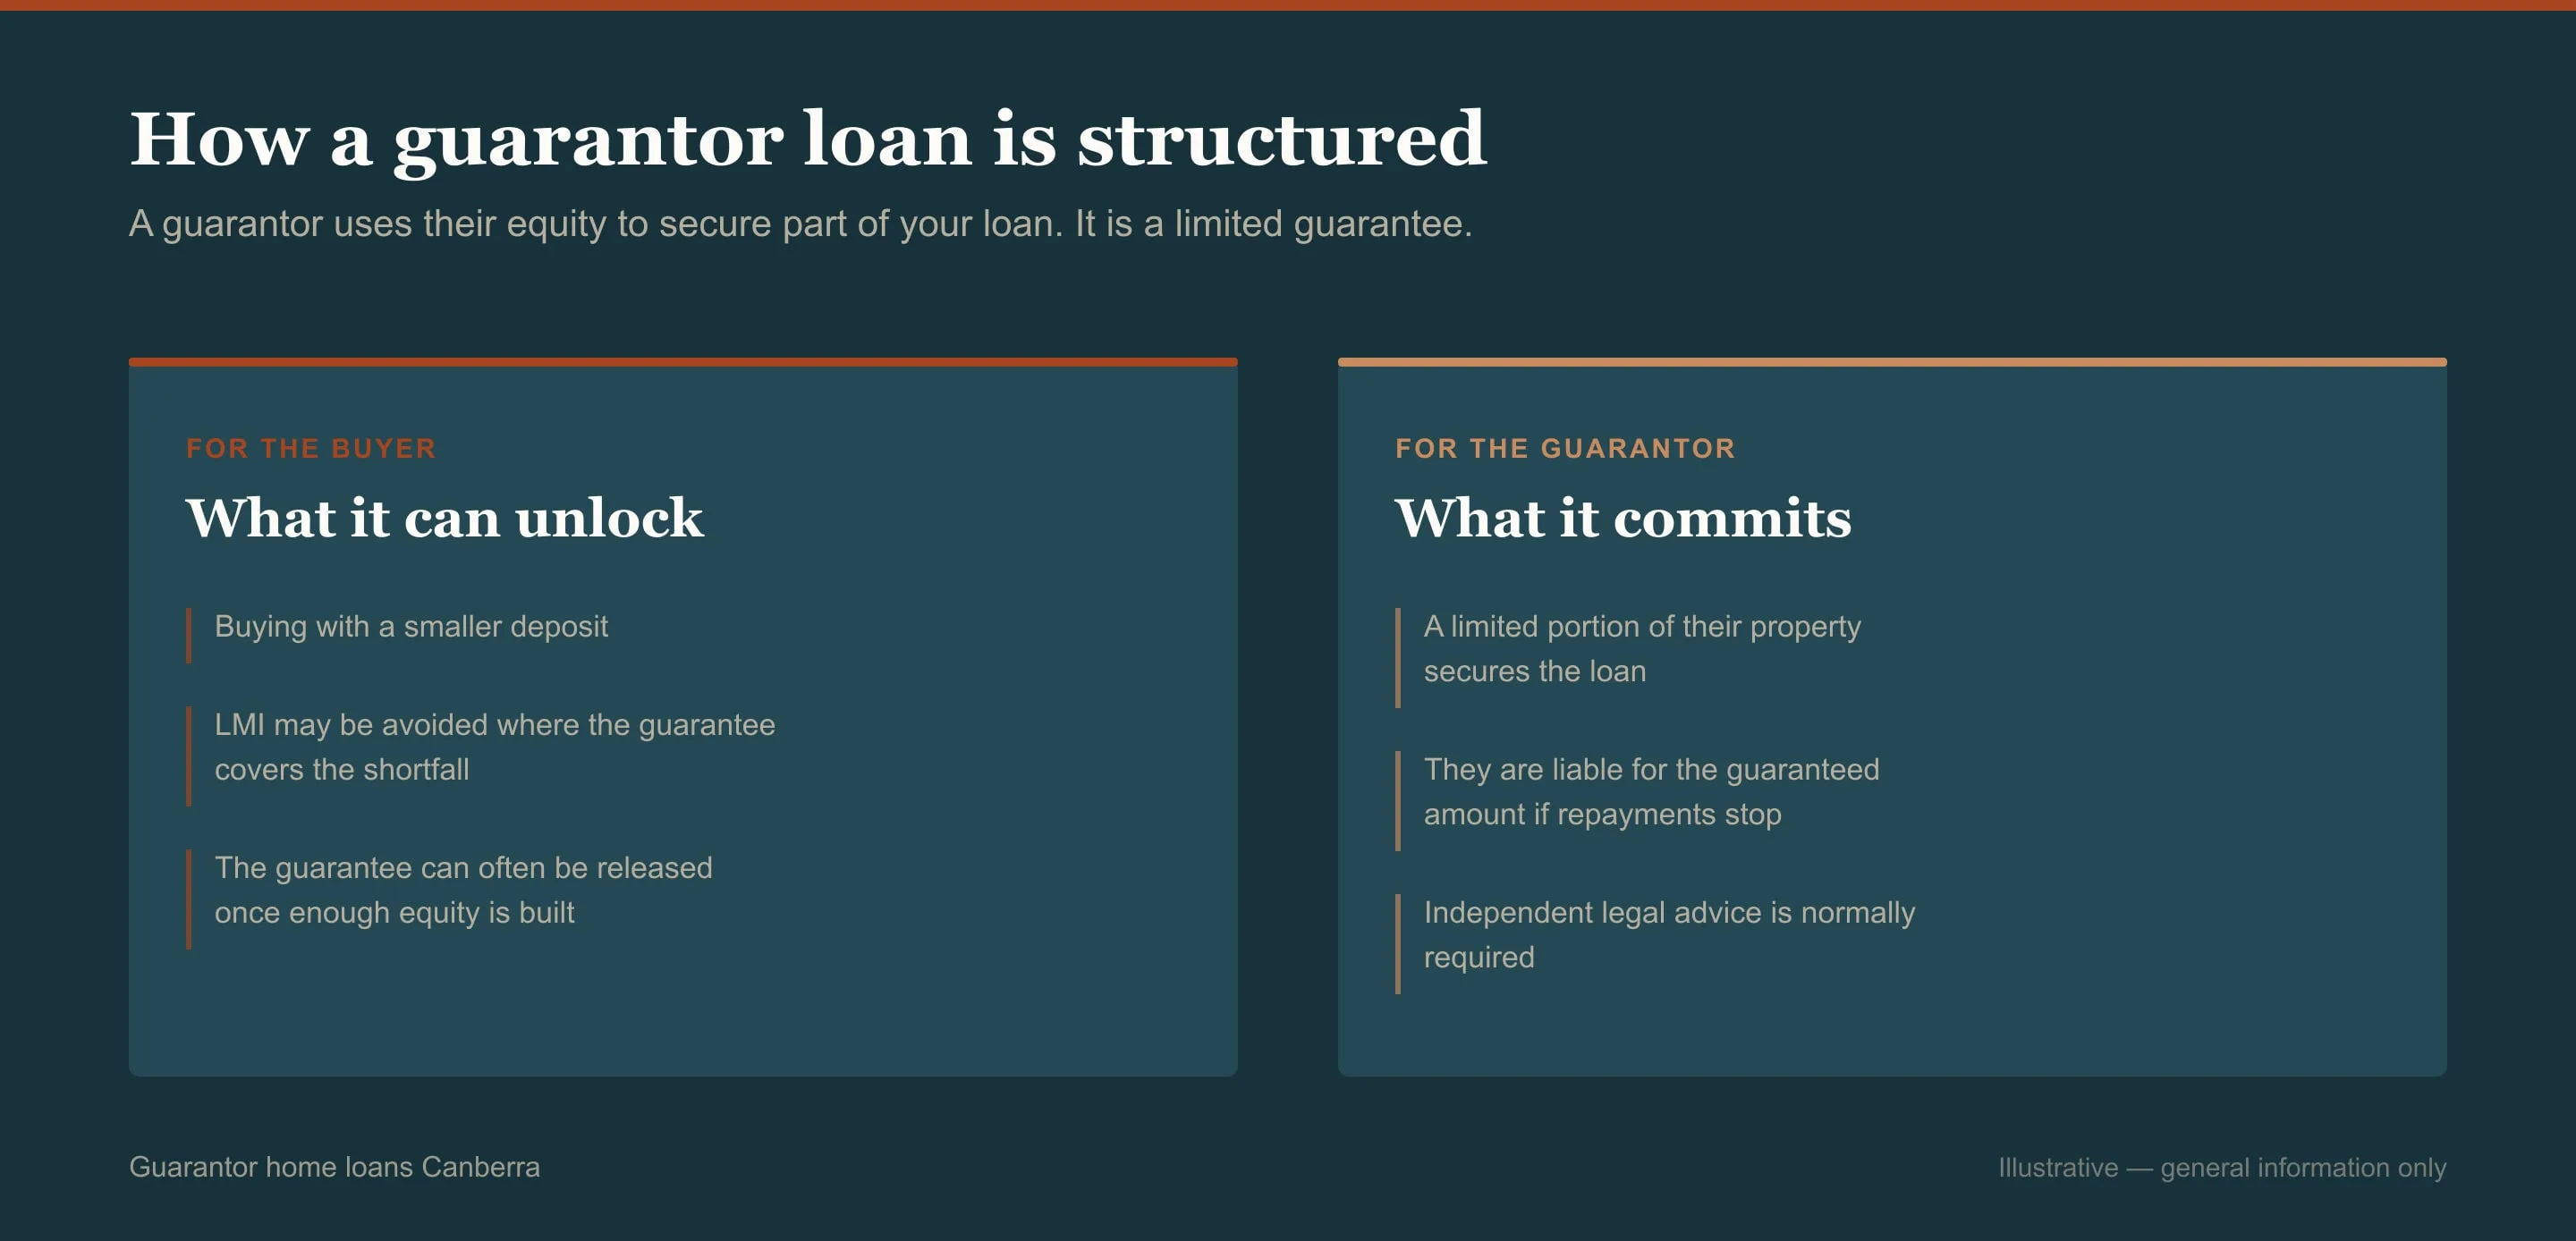
Your guarantor, most often a parent, offers part of the equity in their own property as additional security for your loan, and the lender takes a limited guarantee over that property alongside the mortgage over yours.
Because the lender now holds security across two properties, your combined position sits comfortably below the threshold where Lenders Mortgage Insurance applies. That is what removes the LMI for you, and it is why you can borrow the full purchase price in Canberra with little or no deposit and sometimes the costs on top.
The word doing the work is limited, and it is the one we spend the most time on for you. A properly structured guarantee is capped at a specific amount: enough to bridge your deposit gap and no more. Your guarantor is not guaranteeing the whole loan and should never be asked to, so if a lender or a document in front of you proposes an unlimited guarantee, stop there and call us before signing.
What You Are Asking Your Guarantor To Risk
This is the part that deserves plain language from us rather than reassurance. If you default and the property sells for less than the debt, the lender can call on the guarantee, and your guarantor’s Canberra home is the security standing behind it. They may have to find the guaranteed amount, and in the worst case sell.
Their risk is capped at the guaranteed portion rather than the full loan, which is exactly why we set that amount as low as your deal allows rather than accepting the lender’s first figure. It is not zero risk, and if anyone describes it to you that way they are wrong.
Lenders require your guarantor to obtain independent legal advice, and often independent financial advice, before signing. That requirement exists for good reason and we will not let it be treated as a formality. If your guarantor is retired, or may need to draw on their equity in the next few years, tell us early. Their property is encumbered while the guarantee is in place, which can complicate their own borrowing, downsizing or estate planning, and it may change what we recommend.
How And When We Get Your Guarantor Out
The guarantee is not permanent, and planning the exit with you at the start is what separates a good structure from a lasting problem in the family.
Release generally becomes available once your loan falls below 80% of the value of your own property alone, without your guarantor’s security counted. Two things get you there: paying the loan down, and the property rising in value. Usually both contribute.
The mechanics are a valuation and a formal application to the lender. It is not automatic, and it will not happen simply because time has passed: someone has to ask, and that someone is us. Canberra values have supported release for a lot of families, but that is a market condition rather than a promise, and a flat or falling stretch will extend your timeline.
So we estimate at the outset roughly what has to happen before release becomes available, put that estimate in writing before your guarantor signs anything, and handle the release application ourselves when the time comes.
Which Of The Three Routes We Will Recommend For Canberra Buyers
There are three ways into a property with a small deposit. They are not equally available to you, and which one we recommend turns on your eligibility as much as your preference. We check all three before assuming a guarantee is the answer.
| Route | What it needs | The trade-off |
|---|---|---|
| Family guarantee | A guarantor with sufficient equity, willing to be exposed | No LMI and you can borrow the full price. Puts a family member’s property at risk until release. |
| Federal 5% Deposit Scheme | First home buyer eligibility, property under the ACT price cap | No LMI and no family exposure. Restricted to eligible first home buyers and to properties under the cap. |
| Pay the LMI | Five to ten per cent deposit | Available to anyone who services the loan, with no family involvement. Costs a one-off premium that protects the lender rather than you. |
If you are eligible for the federal scheme and the property sits under the cap, that usually does the same job for you without exposing anyone else, and we will tell you so rather than arranging a guarantee you did not need. The guarantee earns its place above the cap, on a second purchase, or where scheme eligibility does not apply to you. First home buyer scheme detail is on its own page.
What We Check On Both Of You Before Lodging
Both sides of a Canberra guarantee get assessed, so we work through both with you before anything goes to a lender.
- Whether your guarantor has the equity
- They need enough usable equity to cover the guaranteed portion, and if they carry a substantial mortgage of their own they may not have the capacity. We check that first so nobody is asked for something they cannot give.
- How large the guarantee has to be
- We set it to bridge your deposit gap and no more. It is the single most important number in your structure and the one we argue hardest about with the lender.
- Whether you can service the whole loan
- You have to service the full loan on your own income. The guarantee covers your deposit shortfall, not your repayments. We test that before your guarantor is asked to commit to anything.
- Your guarantor’s own position
- Some lenders assess your guarantor’s income and circumstances too, particularly where they are retired or close to it, so we choose a lender whose policy fits the guarantor you actually have.
- The independent advice they must get
- Legal advice for your guarantor is a requirement rather than a suggestion, and some lenders want independent financial advice as well. We tell you which applies and build the time for it into your timeline.
How We Set Your Canberra Guarantor Loan Up
You have two properties, two parties and an extra legal step to get through, so allow a little longer than a standard Canberra purchase. We will tell you how much longer once we know your lender.
-
Both of you, reviewed together
Your income and deposit alongside your guarantor’s equity and position. We would rather have that conversation with everyone in the room than relay it second-hand.
-
Sizing the guarantee
We calculate the smallest guaranteed amount that removes your LMI, and estimate what it will take to release it later, so your guarantor knows both numbers before they decide.
-
The lender chosen on guarantee policy
Guarantee policies differ between lenders. Who counts as an acceptable guarantor and what the release conditions are both vary, so we choose on that rather than on rate alone.
-
Your guarantor takes independent legal advice
They see their own solicitor, not ours. We will not compress this step for you; it is where the arrangement is properly understood.
-
Approval and settlement
Both properties are valued and the guarantee is registered against your guarantor’s title at settlement. We keep both of you told as each step clears.
-
Releasing the guarantee later
Once your loan is under 80% of your property’s value alone, we order the valuation and lodge the release application. Someone has to start that, and it will be us.
Worth having to hand: your income evidence, your savings and the property you are looking at. From your guarantor, a rates notice, their current mortgage position and a rough figure for the equity in their home. Have the conversation with them before the first call, because the guarantee is their decision as much as yours.
Guarantor Home Loans Questions
How does a guarantor home loan work?
Your guarantor offers part of the equity in their property as additional security for your loan. With security across two properties, the lender’s position sits below the level where Lenders Mortgage Insurance applies, so the lender charges you no premium and you can borrow the full purchase price. We cap the guarantee at a set amount rather than letting it cover the whole loan.
Can my parents use their Canberra home as the guarantee?
Yes, provided they have enough usable equity and the lender accepts their position. Parents are the most common guarantors on a Canberra purchase. Their property does not need to be unencumbered, but their own mortgage reduces the equity available to guarantee with.
When can the guarantor be released?
Generally once your loan falls below 80% of your Canberra property’s value counted on its own, without the guarantor’s security. Paying the loan down and any growth in the property both count toward it. Release is not automatic. It requires a valuation and a formal application to the lender, and someone has to start that process.
What happens if I cannot make the repayments?
The lender pursues you and the Canberra property first. If the property sells for less than the debt, the lender can call on the guarantee, and the guarantor’s home is the security behind it. Their exposure is capped at the guaranteed amount rather than the full loan, which is why that amount should be set as low as the purchase allows.
Is a guarantor better than the 5% Deposit Scheme?
If you are eligible for the federal scheme and the property is under the ACT price cap, the scheme usually achieves the same result without exposing a family member, and we will point you at it rather than arrange a guarantee you did not need. A guarantee is the stronger option above the cap, on a purchase that is not your first, or where scheme eligibility does not apply to you. We check all three routes before recommending one.
What does it cost us to have you set this up?
Nothing to have us assess it, size the guarantee and set out the risks for both of you. The lender that writes the loan pays us, and what we are paid is disclosed to you in writing before you proceed. Your guarantor will pay their own solicitor for the independent legal advice the lender requires. That fee is theirs and not ours, and we tell you to expect it up front.
What do you need from us to check whether a guarantee works?
From you, your income evidence, your savings and the property you are looking at. From your guarantor, a rates notice, their current mortgage position and an idea of the equity in their home. Those tell us whether the guarantee works, how large it needs to be and roughly what it will take to release it. Allow a little longer than a standard purchase from there, because of the extra valuation and the legal advice step.
Get The Guarantee Sized Before Anyone Signs
Bring your guarantor into the conversation from the start. They are taking on real exposure and deserve to see the numbers rather than hear about them afterwards. Your position and theirs together tell us whether the guarantee works for the Canberra property you are chasing, the smallest amount it can be set at, what has to happen before it can be released, and which lenders have release conditions worth having. It costs you nothing, and nobody signs anything until you have all four in writing. We do this for families right across Canberra and the border towns.
Ask about guarantor home loans
Nothing here touches your credit file.